Houston Public Adjusters for Commercial and Residential Claims
Get a Full, Documented Claim.
Dependable Claims Specialists - Public Insurance Adjusters (DCS PIA) is a Webster, Texas public adjusting firm and Houston public adjuster serving Greater Houston, Harris and Galveston Counties and the Gulf Coast, licensed statewide in Texas (TX Firm License #3134924) and Florida (FL Firm License #W820363). We work only for policyholders, never for insurers: insurance industry experience since 2010, representing policyholders since 2017. Our public adjusting services start with a free claim review, no recovery no fee, and we respond within one business day.
Licensed public adjusters serving Greater Houston, Texas & South Florida, helping homeowners and businesses near you present a fully documented insurance claim.
When your insurance company sends its adjuster, you can have your own licensed public adjuster. DCS works only for policyholders, not the insurance company.

No Recovery
No Fee
Free
Claim Review
Licensed
TX & FL
Get a Free Claim Review
No obligation. We will call you back, typically within one business day.
Storm Events We Are Helping Texas Families With
If your home or business was damaged in one of these events, we are here when you are ready. Free claim review. No fee unless we recover.
North Texas Tornado Outbreak
Two tornadoes touched down across Wise and Parker counties on the night of April 25: an EF-2 in Runaway Bay and an EF-1 in Springtown. Two lives were lost. Dozens of families were displaced. Our hearts are with North Texas.
Read claim guidanceLeakey, Texas Hail Storm
A supercell dropped hail up to softball size (4.5 inches), per National Weather Service reports, across Leakey, Rio Frio, and Garner State Park. Widespread damage to roofs, vehicles, and ranch structures was reported across the Hill Country.
Read claim guidanceRecent DCS Outcomes
The carrier valued this Hurricane Ian loss below the policy deductible, effectively offering nothing. After the appraisal clause was invoked and DCS served as the policyholder appraiser, the appraisal panel issued an award of $1,427,372.70. The award rested on the inspection, scope, and pricing in the record.
A 50-year State Farm customer had major portions of their Beryl claim denied. A large tree struck the front of the house with multiple limb penetrations and water flowed into seven rooms. DCS documented the full scope, and the partial denial was reversed. The final settlement included a new roof, new A/C unit, and full damage payments.
A Galveston homeowner with Texas Windstorm Insurance Association (TWIA) coverage received an initial offer several times smaller than the actual damage warranted. DCS negotiated the settlement up using detailed documentation and construction knowledge.
A late-December 2024 tornado swept through Spring and damaged the home. The initial Homesite scope captured only a fraction of the actual structural and roof-decking damage. DCS lifted shingles, documented fastener pull-through, and built a supplement that raised the settlement from $21,682.74 to $122,602.83, about 5.65 times the first offer.
Extensive concealed water damage from a failed HVAC condensation line. The initial Homeowners of America offer did not account for the full scope of subflooring, wall cavity, and cabinet damage. DCS documented the cause of the leak and the damage trail and negotiated a final settlement at least 25 times the initial offer.
Allstate denied the plumbing leak claim in full on wear-and-tear grounds. DCS assembled engineering causation evidence, documented the carrier timeline, and negotiated a full reversal to the policy limit.
The initial State Farm offer on a hail-and-roof-leak claim captured only visible surface damage. DCS documented the true scope of roof decking, fastener pull-through, and interior water damage from the resulting leak. The final settlement was about 6.5 times the initial offer.
A tree fell on the home during Hurricane Beryl, causing major structural and interior water damage. DCS was engaged from the first day of the claim and documented dwelling, ALE (loss of use), and personal property across all coverages.
A failed toilet supply line caused extensive water damage across multiple rooms. DCS was engaged from day one and presented a documented claim including subfloor, cabinet, and framing damage.
A plumbing supply line leak caused extensive water damage, but the carrier's initial estimates came in far below the documented restoration scope. Through the formal appraisal process, with DCS serving as the party-appointed appraiser, the panel issued a binding award of $103,598.14 reflecting the documented cost of repair, $76,106.16 above the carrier's initial estimate.
The carrier's initial assessment of this loss was $15,644.10. Through the formal appraisal process, with DCS serving as the party-appointed appraiser, the panel issued a binding award of $97,913.50 reflecting the documented cost of repair, based on the evidence in the record.
The initial Texas Fair Plan scope for this Hurricane Beryl claim came in well below the wind and storm damage. Acting as the public adjuster, DCS documented and negotiated the full extent of the property loss, and the final settlement rose by over $81,000.
Hurricane Ian heavily damaged Sanibel Island, and the carrier's initial offers fell well short of the destruction. Acting as the public adjuster, DCS scoped and negotiated the wind and structural damage, and the final settlement rose by over $181,000 to cover the rebuild.
Results vary and are not guaranteed. Each outcome shown reflects the facts, policy, and documentation of that specific claim. An appraisal award is an amount-of-loss determination and is not necessarily payment or the policyholder's net recovery.
Results vary and are not guaranteed. Every claim depends on its own policy, facts, and carrier evaluation.
Pre-Storm Guides for Texas & Florida Policyholders
Atlantic hurricane season runs June 1 through November 30. State-specific guides from licensed Texas and Florida public adjusters. Educational only, not legal advice.
Texas Homeowner Hurricane Prep 2026
TWIA + the 14 designated coastal counties + Harvey, Ike, and Beryl lessons. The one-week pre-storm plan for Texas Gulf Coast families.
Read the guideFlorida Homeowner Hurricane Prep 2026
Citizens + the Valued Policy Law + lessons from Andrew, Irma, and Ian. The Florida-specific pre-storm playbook.
Read the guideTexas Commercial Hurricane Prep 2026
TWIA commercial wind, Business Interruption, and the documentation a commercial file needs. The Texas-specific commercial playbook.
Read the guide8 Endorsements That Quietly Limit Your Claim
ACV roof, cosmetic exclusion, percentage hurricane deductible, anti-concurrent causation: the endorsements that reduce claim payouts.
Read the guideYou Paid for This Coverage.
DCS Helps You Present the Claim.
Your insurance company has adjusters, engineers, and attorneys on its side. Hiring a public adjuster is optional, but it puts a licensed professional with claims experience on yours.
Our founder spent years working inside the insurance industry, handling claims as a field adjuster and team lead before becoming a licensed public adjuster in 2017. Combined with a background in construction and remodeling going back decades, DCS understands property damage from the foundation up.
DCS guides you through the policy obligations, documents the loss, and negotiates the claim under the terms of your policy. Whether you are in Houston, Fort Lauderdale, or anywhere in our service area, DCS is a public adjuster near you.
Learn More About DCS PIASince 2010
Insurance Industry Experience
Since 2017
Licensed Public Adjuster
Millions
Recovered in Documented Cases
24/7
Emergency Line (After-Hours Routing)
Residential Claim Types
From hurricanes to house fires, we handle all types of residential property damage claims across Texas and Florida.
Fire & Smoke Damage
Learn More
Plumbing Leak
Learn More
Water Damage
Learn More
Mold Damage
Learn More
Accidental Damage
Learn More
Theft Claims
Learn More
Vandalism Claims
Learn More
Denied Claims
Learn More
Hail Damage
Learn More
Storm & Wind Damage
Learn More
Hurricane Damage
Learn More
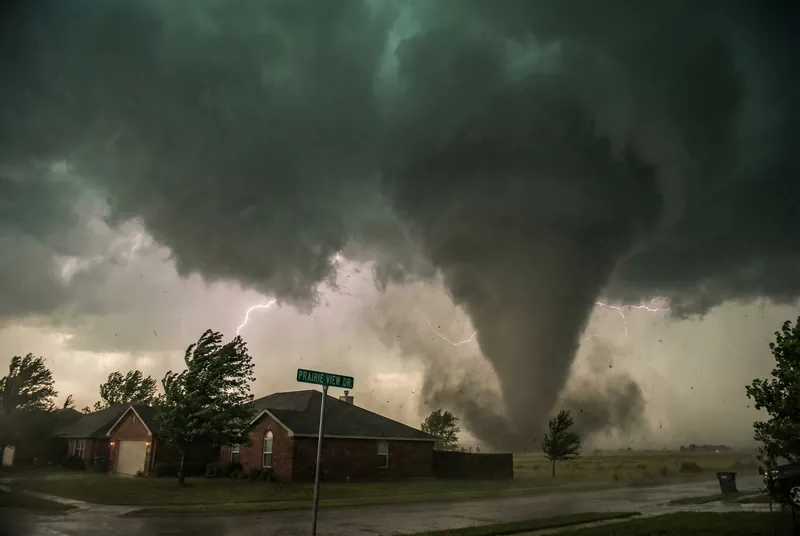
Tornado Damage
Learn More
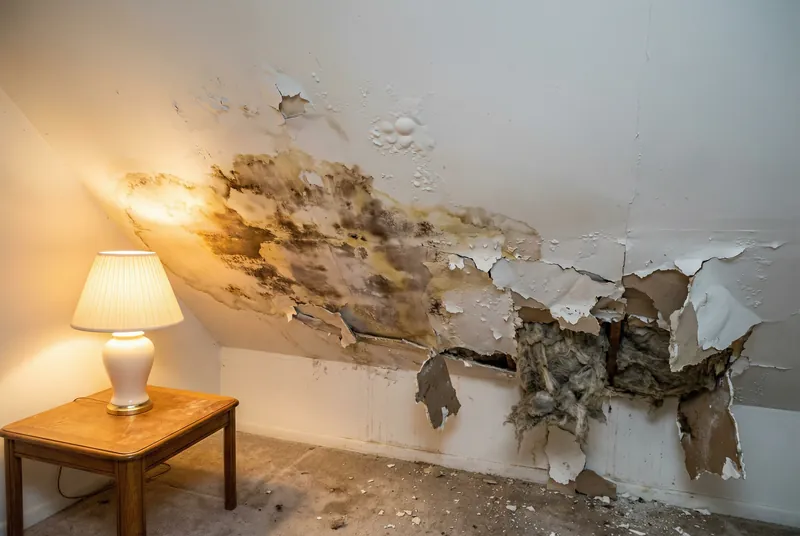
Roof Leak
Learn More
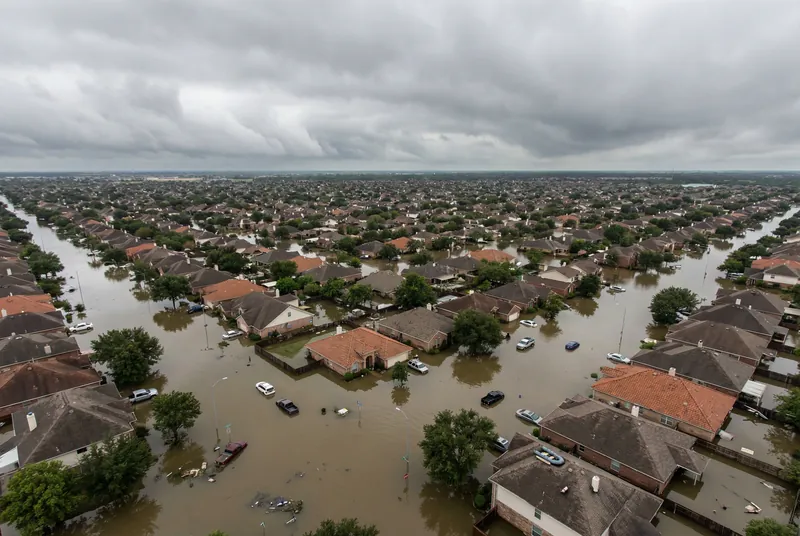
Flood Damage
Learn More
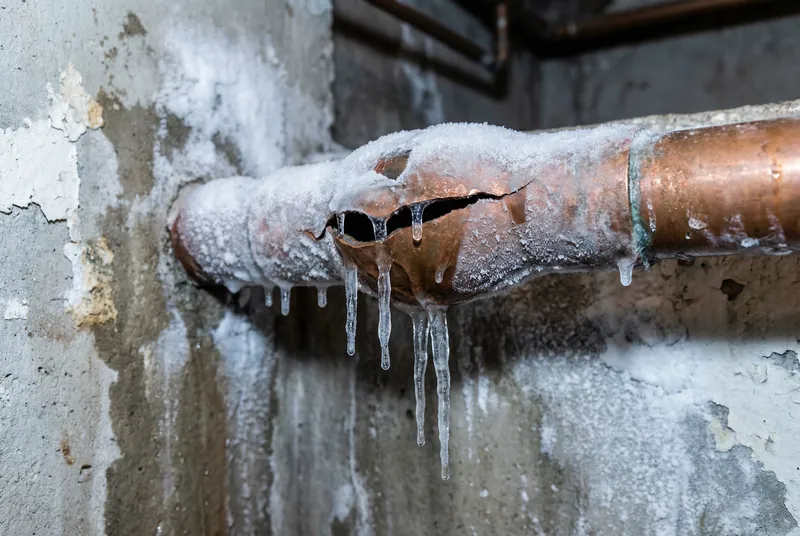
Freeze Damage
Learn More
Lightning Damage
Learn More
Commercial Claim Types
Commercial property claims are complex. DCS handles everything from small business losses to large industrial properties.
Commercial Fire & Smoke
Learn More
Commercial Plumbing
Learn More
Commercial Property
Learn More
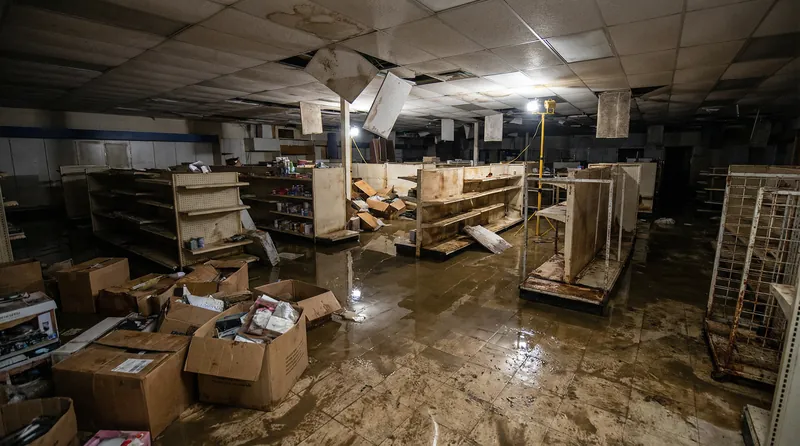
Commercial Water Damage
Learn More
Business Interruption
Learn More
Commercial Building
Learn More
Denied Commercial Claims
Learn More
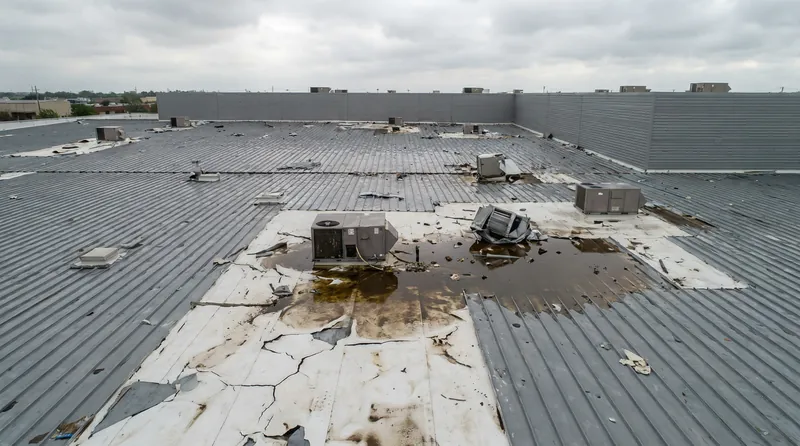
Commercial Roof Damage
Learn More
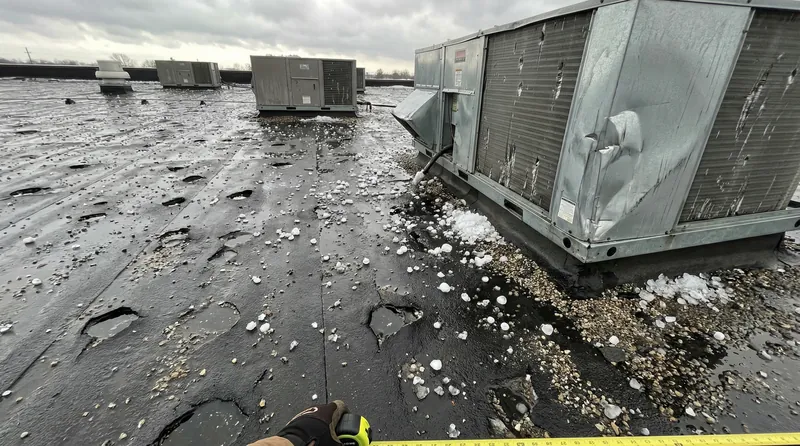
Commercial Hail
Learn More
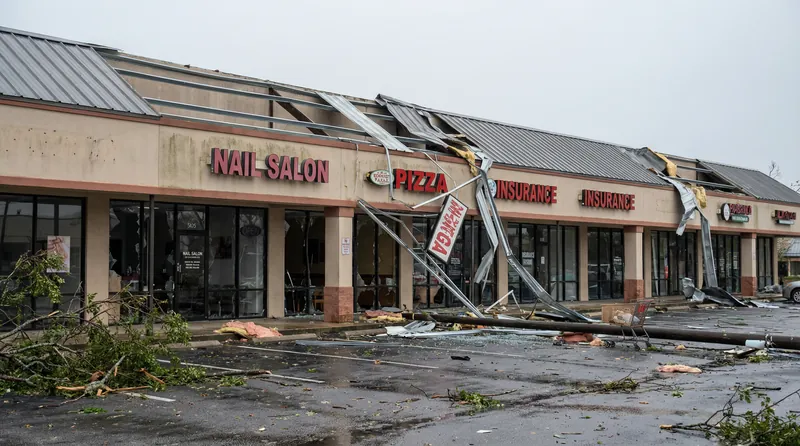
Commercial Hurricane
Learn More
What to Do Immediately After a Loss
The steps you take in the first 24 to 72 hours after a property loss can affect your claim. Your policy is a contract, and it requires you to fulfill certain duties. DCS can help you document and organize the claim.
Ensure Safety First
Before anything else, make sure everyone is safe. If the structure is unsafe, do not enter. Contact emergency services if needed, then call us.
Report Your Loss Promptly
Notify your insurance company of the loss as soon as possible. Your policy requires prompt reporting. Delays can complicate your claim.
Document Everything
Take as many photos and videos as possible. There is no such thing as too many. Photograph every room, every angle, every damaged item before anything is moved or cleaned up.
Preserve Evidence Safely
Preserve damaged items for inspection when safe and practical. Follow public-health and qualified professional guidance for contaminated or hazardous materials. Photograph and inventory items safely before necessary disposal when possible; do not keep unsafe items merely for an inspection.
Track Every Expense
Keep receipts for every expense related to the loss, including temporary repairs, hotel stays, meals, and storage. These costs may be reimbursable under your policy.
Prevent Further Damage
Make reasonable temporary repairs to prevent additional damage, such as tarping a damaged roof or boarding broken windows. Keep all receipts. Your policy requires you to mitigate further loss.
Know Your Policy Duties
Your policy is a contract with obligations on both sides. You must cooperate with the investigation, provide a signed proof of loss, and submit to an examination under oath if requested. DCS can help organize damage records and claim documents. Ask your attorney about legal requirements and examination-under-oath preparation.
Get Appropriate Document Review
Before signing a release or a document described as a final settlement, ask a licensed attorney about its legal effect. DCS can review the damage estimate and payment history and provide supporting claim documents. Public adjusters do not provide legal advice.
Not sure what to do next? Call us right now. We will walk you through every step at no charge.
Why Choose Dependable Claims Specialists?
DCS brings carrier-side experience and construction expertise to every claim it handles.
Works Only for Policyholders
We never work for insurance companies. Our only job is to represent the policyholder and present the documented claim.
Insider Industry Knowledge
Our founder worked as a field adjuster and team lead for insurance carriers from 2010 to 2017. That experience shows how carriers evaluate claims.
Construction Experience
With a background in construction and remodeling going back decades, DCS understands repair costs and documents damage that is easy to miss.
Licensed to Handle Your Claim
Other than representing yourself, the only paid third parties who may negotiate a property claim on a policyholder's behalf are a licensed public adjuster or an attorney under Texas and Florida licensing law (Tex. Ins. Code Ch. 4102; Fla. Stat. §626.854). Contractors do the rebuilding. When coverage disputes, underpayments, or policy application issues arise, a licensed public adjuster or attorney can act for the policyholder.
We Manage the Claim File
From the initial inspection to the final settlement, DCS manages the claim file so you can focus on your family.
No Recovery, No Fee
You pay nothing upfront. Our fee is a percentage of the recovery, so no recovery means no fee.
Our 4-Step Process
DCS handles the paperwork and the carrier communication so you can focus on your family.
Free Consultation
Contact us for a free, no-obligation review of your policy and property damage. DCS will tell you whether it can help.
Property Inspection
DCS inspects your property and documents the damage, including what is hidden.
Claim Preparation
We prepare a documented claim package and submit it to your insurance company on your behalf.
Settlement
We negotiate directly with your insurer on the documented loss under your policy.
What Our Policyholders Say
Steve Saxenian
5 months ago
“Josh did the best job possible on my Beryl claim. Very professional and very very meticulous. He negotiated a settlement several times the amount the insurance company initially came up with due to his perseverance and knowledge of construction. Really the best decision I've made in years.”
John Brau
5 months ago
“Dependable Claims Specialist (DCS) saved us! We have had State Farm Ins. for more than Fifty (50) years, and State Farm was denying major parts of our claim. We were totally frustrated until Josh Osteen at Dependable Claims Specialist came to our rescue. Josh has some of the most sophisticated equipment I have ever seen; he used this to document the damage and calculate the proper amount for the claim. With his help, we were able to get a new roof, new A/C unit and fair payments for the serious damage done by Hurricane BERYL.”
Maria Deras
6 months ago
“When Hurricane Beryl hit and a tree fell on our house in Spring, we were completely overwhelmed. Josh stepped in and took all the stress off of us. He explained everything clearly and made sure our home, ALE, and personal property were covered, over $240,000 in total. It was such a relief knowing we were taken care of. I would recommend him to any family dealing with insurance.”
Were we helpful? Share your experience.
Areas We Serve in Texas and Florida
Licensed statewide in Texas and Florida. DCS accepts claims across both states following a review of the file. The counties below are where we work most often, from the Greater Houston area to South Florida.
Harris CountyPrimary
Montgomery CountyPrimary
Galveston CountyPrimary
Brazoria CountyPrimary
Chambers CountyPrimary
Fort Bend County
Liberty County
Waller County
Palm Beach CountyPrimary
Broward CountyPrimary
Miami-Dade CountyPrimary
Lee County
Collier County
Do not see your city? Contact us to confirm service availability in your area.
Frequently Asked Questions
Does Your Policy Cover What You Think It Does?
Many homeowners do not read their insurance policy until they have a loss, and by then the policy terms are fixed. Endorsements, exclusions, and limitations in the policy can reduce a payment by tens of thousands of dollars.
Actual Cash Value vs. Replacement Cost
If your policy pays ACV instead of replacement cost, you could receive the depreciated value of a 15-year-old roof, not what it costs to replace it. The difference can be $20,000 or more.
Separate Wind and Hail Deductibles
In Texas, many policies have a wind and hail deductible of 1 to 5 percent of your dwelling coverage. On a $300,000 home, that is up to $15,000 out of pocket before coverage applies.
Flood Is Not Covered
Standard homeowners policies do not cover flood damage. If you are in or near a flood zone and do not have a separate flood policy, you have no coverage for rising water.
Roof Age Limitations
Some policies limit or exclude coverage for roofs over a certain age, or pay only actual cash value on older roofs regardless of the rest of your policy.
Read the Policy Before You Need It
A policy pays according to its terms, and those terms are set before the loss. DCS reads the policy and presents the claim under the coverage it provides.
Whether a loss is covered depends on the policy language and the facts of the loss.
Helpful Resources
Blog
What to Do After a Hurricane
Step-by-step guide for homeowners after storm damage.
Blog
Public Adjuster vs Insurance Adjuster
Know the difference and why it matters for your claim.
Blog
Claim Denied? Your Options
What to do when your insurance company denies your claim.
FAQ
Frequently Asked Questions
Answers to the most common questions about public adjusters.
Ready for a Second Look at Your Claim?
Schedule a free, no-obligation consultation with a licensed public adjuster near you today. No recovery, no fee. No upfront cost to you.
