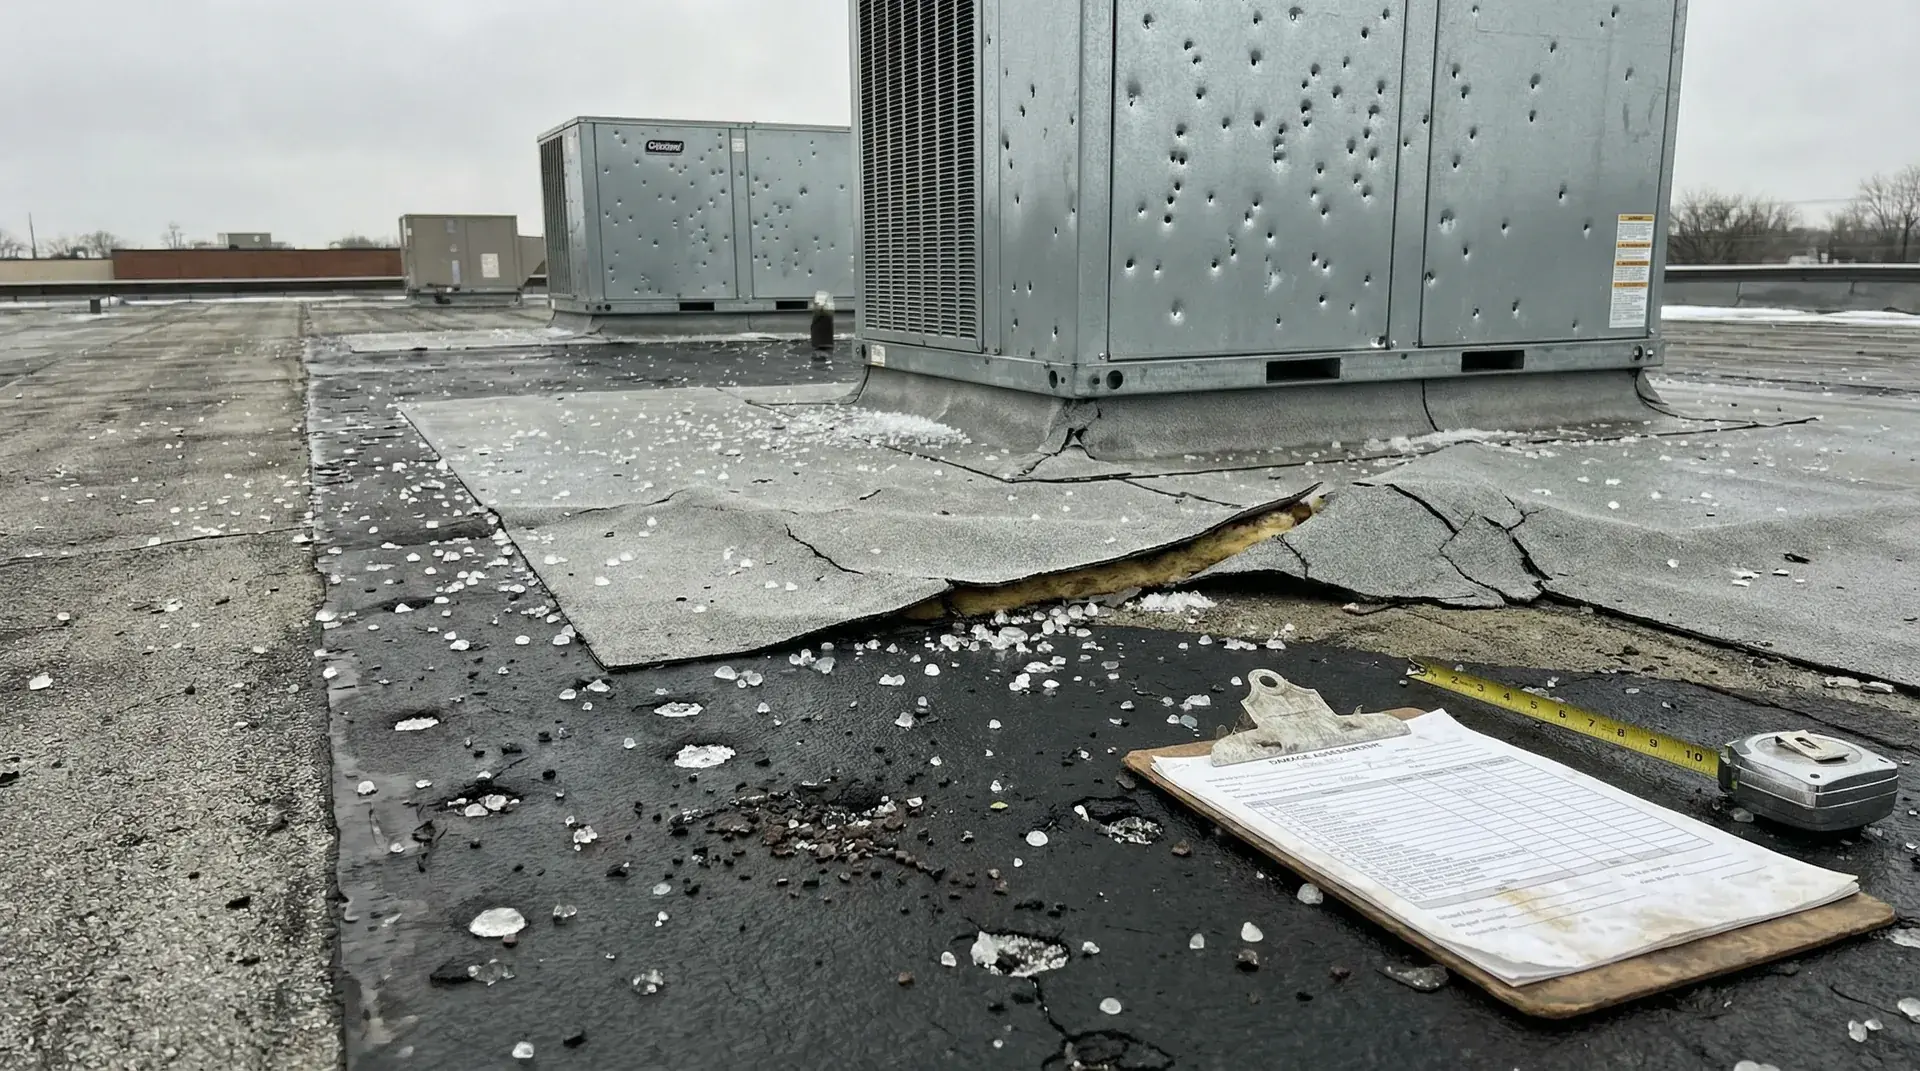
Stop the Damage Now - Dispatch a commercial roofing contractor experienced with insurance hail inspections
Hail damage to TPO, modified bitumen, and metal commercial systems is technical to document. An inspection now establishes the date-of-loss scope before later weather muddies it.
Most standard property policies obligate the insured to take reasonable steps to mitigate further damage. Failing to do so can give the carrier grounds to reduce or deny the claim.
Independent referral - no fees, no commissions. DCS does not accept any compensation from network vendors. Vendors typically bill their work to the insurance claim; coverage depends on your policy and the claim outcome. Recommendations are based on what is best for your claim, not on who pays us.
Quick Answer
For commercial properties, carriers routinely misclassify membrane fractures as 'aesthetic' to avoid massive flat-roof replacements. A fractured membrane is a functional failure. DCS utilizes core sampling and infrared scans to document functional system failure, working to support a settlement that covers full system replacement and necessary code upgrades where the damage warrants it.
Commercial Hail Damage Requires Expert Documentation
Commercial buildings present unique hail damage challenges. Large flat roofing systems, extensive HVAC equipment, skylights, metal panels, and other commercial-specific components require specialized knowledge to inspect and document properly.
Insurance adjusters working high-volume claims after a major hail event may rush inspections and miss damage that adds up to tens of thousands of dollars on a commercial property.
We conduct thorough, methodical inspections of every surface that hail can reach on your commercial property and document everything with the detail your claim requires.
- Toll Free:833-4UR-LOSS
- Texas Office:936-522-6627
- Florida Office:954-849-3405
Common Damage Types We Document
- Commercial Roofing Systems: Damage to TPO, EPDM, modified bitumen, metal, and other commercial roofing systems from hail impact.
- HVAC and Mechanical: Damaged coils, bent fins, and reduced efficiency in rooftop HVAC units and other mechanical equipment.
- Metal Panels and Cladding: Dents and damage to metal wall panels, fascia, and other exterior metal components.
- Skylights and Glazing: Cracked or broken skylights, damaged window glazing, and compromised seals.
How Hail Damages Commercial Roofing Systems - and Why It Is Routinely Missed
Commercial roofing systems protect large flat or low-slope surfaces and respond to hail very differently from residential shingles. Impacts on TPO and EPDM membranes may leave no visible puncture while causing delamination, mat fracture, and reinforcement bruising that lead to premature failure. On metal panels, hail fractures factory coatings and exposes substrate to corrosion even when the dent looks superficial. Modified-bitumen systems lose surface granules that protect the membrane from UV. Hail also dents condenser fins and deforms coils on rooftop HVAC, quietly reducing efficiency and equipment life. Infrared scanning can reveal moisture already migrating into the assembly, and core sampling confirms membrane integrity. A complete commercial hail assessment requires a hands-on rooftop inspection, not a view from the parking lot.
- Hail damage to commercial roofing is frequently underestimated by adjusters not trained on flat-roof membrane systems.
- Membrane delamination and mat fracture from hail often have no visible puncture and require infrared or core-sample documentation.
- Some policies limit coverage for cosmetic hail damage. We document what the hail did to the roof so the insurer can apply your policy to the facts.
- Equipment Breakdown coverage may respond to a covered sudden mechanical, electrical, or pressure-system breakdown, if that coverage is included. It is not a maintenance warranty. Wear, deterioration, exterior storm damage, and resulting losses must be evaluated under the specific property and breakdown forms and their exclusions. We document the failed component and mechanism so each insurer can review its part of the loss.
What Your Commercial Property Policy Covers on a Hail Loss - and the Endorsements, Deductibles & Caps That Decide the Payout
A commercial hail claim is won or lost on policy details that rarely surface until a storm hits. These are the endorsements, deductibles, and provisions that most often move the number on a Texas or Florida commercial hail claim - and how DCS handles each.
Cosmetic Damage Exclusion recasts functional hail as "appearance only"
Many commercial property policies carry a Cosmetic Damage Exclusion (CDE) endorsement that excludes hail damage affecting only appearance while function is preserved. Carriers invoke it on dented metal panels and membrane systems, arguing the roof still sheds water. The exclusion has two prongs - damage must affect appearance AND not impair function - so DCS documents fractured coatings, mat fracture, compromised seams, and accelerated failure to defeat a misapplied cosmetic label.
Functional hail damage to membranes is invisible from the surface
Hail impacts on TPO, EPDM, and modified-bitumen membranes frequently cause delamination, mat fracture, and reinforcement bruising with no visible puncture. Adjusters working high-volume storm rosters miss it from a single ladder. DCS uses infrared scanning and core sampling so the membrane damage is documented as a functional system failure, not waved off as 'no visible damage.'
Percentage wind/hail deductibles can swallow six figures
Commercial hail losses are commonly subject to a separate percentage deductible (often 1%-5% of the insured building value) rather than a flat dollar amount. On a multi-million-dollar building that first slice of loss is the owner's responsibility before coverage triggers. DCS confirms the deductible basis on the declarations and builds the scope to full replacement value, not trimmed to barely clear the deductible.
Ordinance or Law pays the code-required roof upgrade
A hail-damaged commercial roof frequently must be rebuilt to current code - added insulation R-value, improved drainage, secondary water barriers, or a different assembly. The base policy pays like-for-like; Ordinance or Law coverage (Coverages A, B, and C) pays the demolition of undamaged portions and the increased cost of code compliance. These limits are separate and commonly underused, so DCS identifies the code triggers and claims the upgrade cost.
HVAC and rooftop equipment damage is part of the same loss
Rooftop HVAC units, vents and other permanently installed equipment are generally part of the building under commercial property forms, so hail damage to them belongs in the same claim as the roof. We document coil and fin damage, housings and any loss of function, and check the policy for any cosmetic-damage exclusion.
RCV vs. ACV and roof age/condition limitations
Replacement-cost coverage generally values covered repair or replacement without depreciation, subject to the policy terms, limits, deductible, and any replacement conditions or roof-age endorsements. It does not automatically require complete roof or building replacement. Actual-cash-value coverage generally includes depreciation that is not recoverable under that valuation. DCS documents the repair scope and reviews the applicable valuation provisions.
Repair-vs-replace and matching across the roof field
Carriers often push a spot repair when the correct scope - under manufacturer warranty terms and NRCA standards - is a full system replacement, especially where a partial repair voids the warranty or cannot be matched on a weathered or discontinued membrane. DCS documents the warranty and matching constraints and argues the appropriate replacement scope.
Business income while the roof is open and being replaced
If hail damage and the replacement work suspend or curtail operations, Business Income and Extra Expense coverage can apply for the period of restoration. DCS coordinates the roof scope with the time-element claim so the restoration timeline used for the building also supports the income-loss period.
Coverage varies by carrier, policy form, and endorsement. These are common patterns in Texas and Florida homeowner and commercial property policies - not a description of your specific policy. Review your declarations page and endorsements, or have DCS review them with you. Educational information, not legal advice.
Handling the Claim Yourself vs Engaging DCS PIA
Texas policyholders can negotiate their own claim. Hiring a licensed public insurance adjuster is optional. The table below sets out, side by side, how the same claim tasks get done in each path so you can make an informed decision.
| Claim handling task | Self-represented | DCS PIA representation |
|---|---|---|
| A dated record of the claim | A manual calendar and a memory of phone calls; hard to reconstruct months later. | Every carrier contact, request, inspection and payment logged and timestamped from day one. |
| Scope of loss documentation | Photos plus a written list; rarely matches the carrier's estimating system line-by-line. | Xactimate estimate built in the same software the carrier uses, line-item-matched to scope. |
| Hidden or secondary damage assessment | You decide what to document. | Moisture mapping, thermal imaging, and engineering referrals when warranted; ensuing-loss tracking. |
| Appraisal clause invocation when valuation differs | Available to any insured under the policy appraisal clause. | Invoked when carrier scope materially undervalues the loss; appraisal and umpire fees disclosed up front. |
| Supplement filings for damage discovered during repair | You prepare the claim. | Tracked through repair; supplement scopes filed against the carrier as new damage is exposed. |
| Additional Living Expense / Extra Expense documentation | Receipts assembled at the end of displacement, often incomplete. | Receipt and mileage log discipline from day one; ALE / Extra Expense submitted per policy form. |
| Mold sub-limit endorsement pursuit | Your choice. | Mold cause, species, and remediation protocol documented to IICRC S520; sub-limit pursued. |
| Fee structure | No third-party fee. You handle the claim yourself. | In Texas: no recovery, no fee, and the public adjuster fee is capped under Tex. Ins. Code § 4102.104. Florida claims follow a separate written agreement. Hiring a public adjuster is optional. |
Educational comparison, not legal advice. Hiring a Texas-licensed public insurance adjuster is optional and capped at 10% of the recovery under Tex. Ins. Code § 4102.104. Public adjusters represent policyholders on claim valuation and negotiation. Legal claims for bad faith or prompt-payment damages are handled by attorneys, not public adjusters.
Tips That Protect Your Claim
Document All Damage Before Repairs
Photograph every damaged surface, every dented HVAC unit, and every affected area of your building before repairs begin, when it is safe. Do not delay emergency repairs. Date-stamped photos are valuable evidence.
Document and Coordinate Permanent Repairs
Document damage before repairs when safe, notify the insurer, and give it a reasonable opportunity to inspect. Do not delay urgent safety work or reasonable steps to prevent further damage. Keep photos, records, and receipts; coordinate disputed permanent-repair timing with qualified professionals and your insurer.
Obtain a Storm Date Confirmation
We can obtain independent weather data confirming the date, size, and intensity of the hailstorm at your property address. This documentation is important for establishing storm causation.
Have HVAC Equipment Professionally Assessed
Have a qualified HVAC technician assess all rooftop units after a hail event. Hail damage to HVAC equipment can reduce efficiency and shorten equipment life even when it does not cause immediate failure.
Consider Business Interruption Exposure
If hail damage requires your business to suspend or limit operations, document the impact on your revenue and expenses from the first day of interruption.
Do Not Accept the First Offer
Initial settlement offers after hail events are often based on a limited inspection. Contact us before accepting any payment to make sure the full scope of damage has been captured.
Critical: Document the Damage Before Permanent Repairs
Protect people first, notify your insurer promptly, and document damage before repairs when safe. Take photos or video, keep receipts, and give the insurer a reasonable opportunity to inspect before nonurgent permanent repairs where practical. Do not wait for a claim to settle before addressing urgent safety needs or preventing further damage. Follow qualified professional and public-health guidance for contaminated or hazardous materials; document them safely before disposal when possible, but do not keep unsafe items merely for an inspection.
What to Do Right Now
Apply temporary protective measures to prevent water intrusion, and keep all mitigation receipts.
Contact your insurance carrier to report the loss and obtain a claim number.
Document every damaged surface, dented HVAC unit, skylight, and panel with date-stamped photos and video.
Have a qualified HVAC technician assess all rooftop units for fin and coil damage.
Obtain certified weather data confirming the hail date, size, and intensity at your property address.
Request infrared scanning or core sampling to document concealed membrane and moisture damage.
Contact DCS PIA before signing any documents or accepting any settlement offer.
Why Professional Representation Matters
Commercial roofing systems require specialized knowledge that high-volume storm adjusters frequently lack.
Cosmetic Damage Exclusion endorsements are routinely misapplied to functional membrane and panel damage.
Percentage wind/hail deductibles can swallow six figures, so the scope must be built to full replacement value, not trimmed to clear the deductible.
Ordinance or Law code-upgrade costs are commonly omitted from initial estimates on roof replacements.
Rooftop HVAC and equipment damage is easily overlooked when the focus stays on the roof field.
Early acceptance of a limited inspection can leave you responsible for a full system replacement the policy may cover.
The insurance company has a team of professionals working for them. You deserve one working for you.
Why Policyholders Trust DCS PIA
We bring carrier-side experience, construction expertise, and genuine care to every claim.
We have experience inspecting all types of commercial roofing systems.
We document functional damage to counter cosmetic-only classifications.
We obtain independent weather data to confirm storm dates and hail size.
Our founder worked inside the insurance industry and knows how commercial claims are evaluated.
We are fully licensed and bonded in Texas and Florida.
No recovery, no fee. You pay us nothing unless we help you recover money.
We handle every step from inspection to final settlement.
We help you understand and fulfill every obligation under your policy.
Frequently Asked Questions
Related Texas Claim Types We Handle
Property losses rarely fall into a single category. Explore related claim types DCS PIA documents and negotiates for Texas policyholders - each handled on a no recovery, no fee basis.
More Related Claim Types
A Property Claim Is a Process With Tripwires - Not Just a Form
Filing is the easy part. Once you report a loss, the carrier runs a process governed by your policy’s conditions and by timelines that move faster than most people expect - and most underpaid and denied claims trace back to a single step the policyholder never knew was load-bearing.
A commercial hail claim turns on policy mechanics most owners never read until a storm hits - a Cosmetic Damage Exclusion that recasts functional membrane and panel damage as 'appearance only,' a percentage wind/hail deductible that swallows the first six figures, and Ordinance or Law limits that decide whether the code-required roof upgrade is paid.
Duties After Loss
Policies impose duties after loss, which may include prompt notice, reasonable protection from further damage, records and cooperation. Follow the requirements in your policy. The effect of any alleged failure depends on the policy, facts and law; ask an attorney about legal consequences or an examination under oath.
Reservation of Rights (ROR)
A reservation-of-rights letter means the carrier is investigating while reserving the right to deny coverage later. It signals the claim is contested - not a settlement - and it changes how every photo, statement, and estimate should be handled from that point forward.
Request for Information (RFI)
Carriers send repeated requests for documents, receipts, measurements, and recorded statements. Incomplete or late responses stall the file and become the carrier’s stated reason to delay payment or pay less than the loss is worth.
Proof of Loss (POL)
A sworn proof of loss is a signed, deadline-bound itemization of your damages. Understate it, overstate it, or miss the deadline, and the figure on that form can be used to cap - or contest - your recovery.
A claim moves at the speed of its documentation. Your policy sets out what you agreed to do after a loss - report it promptly, protect the property from further damage, keep records, and provide the information your carrier asks for. Meeting those obligations, with a scope that reflects the real damage, is what keeps a claim moving. That documentation work is exactly what a licensed public adjuster does.
Each of these is a place a legitimate claim quietly loses value. This is why policyholders hire DCS PIA - Dependable Claims Specialists, licensed public insurance adjusters - to document the loss, build the proof of loss, answer the carrier’s requests on time, and negotiate the valuation correctly from day one. You handle one claim in your life; the carrier handles thousands. A public adjuster levels that.
DCS represents policyholders on claim valuation and negotiation. Interpreting your legal rights, bad-faith, and litigation are matters for a licensed attorney - not a public adjuster. This is general educational information, not legal advice.
Educational Information - Not Legal Advice
The information on this page is for general educational purposes only. Dependable Claims Specialists is a licensed public adjusting firm - not a law firm. Public adjusters help policyholders inspect, document, evaluate, and negotiate property insurance claims, which includes reading and applying your policy in the ordinary course of adjusting (coverage parts, exclusions, endorsements, scope). We do not practice law and we do not provide legal advice. For legal opinions, demand letters, Chapter 542A pre-suit notices, statutory remedies under the Insurance Code, or litigation, consult a licensed attorney in your state. Texas public adjusters operate under TX Ins. Code Chapter 4102; Florida public adjusters operate under FL Statute §626.854.
